VARMAX models#
This is a brief introduction notebook to VARMAX models in statsmodels. The VARMAX model is generically specified as:
where \(y_t\) is a \(\mathrm{k_endog} \times 1\) vector.
[1]:
%matplotlib inline
[2]:
import pandas as pd

import statsmodels.api as sm
[3]:
import shutil

import requests


def download_file(url):
    local_filename = url.split("/")[-1]
    with requests.get(url, stream=True, timeout=30) as r:
        with open(local_filename, "wb") as f:
            shutil.copyfileobj(r.raw, f)

    return local_filename


filename = download_file("https://www.stata-press.com/data/r12/lutkepohl2.dta")

dta = pd.read_stata(filename)
dta.index = dta.qtr
dta.index.freq = "QS"
endog = dta.loc["1960-04-01":"1978-10-01", ["dln_inv", "dln_inc", "dln_consump"]]
Model specification#
The VARMAX class in statsmodels allows estimation of VAR, VMA, and VARMA models (through the order argument), optionally with a constant term (via the trend argument). Exogenous regressors may also be included (as usual in statsmodels, by the exog argument), and in this way a time trend may be added. Finally, the class allows measurement error (via the measurement_error argument) and allows specifying either a diagonal or unstructured innovation covariance matrix (via the
error_cov_type argument).
Example 1: VAR#
Below is a simple VARX(2) model in two endogenous variables and an exogenous series, but no constant term. Notice that we needed to allow for more iterations than the default (which is maxiter=50) in order for the likelihood estimation to converge. This is not unusual in VAR models which have to estimate a large number of parameters, often on a relatively small number of time series: this model, for example, estimates 27 parameters off of 75 observations of 3 variables.
[4]:
exog = endog["dln_consump"]
mod = sm.tsa.VARMAX(endog[["dln_inv", "dln_inc"]], order=(2, 0), trend="n", exog=exog)
res = mod.fit(maxiter=1000, disp=False)
print(res.summary())
                             Statespace Model Results
==================================================================================
Dep. Variable:     ['dln_inv', 'dln_inc']   No. Observations:                   75
Model:                            VARX(2)   Log Likelihood                 361.039
Date:                    Tue, 27 Oct 2026   AIC                           -696.078
Time:                            22:09:22   BIC                           -665.951
Sample:                        04-01-1960   HQIC                          -684.049
                             - 10-01-1978
Covariance Type:                      opg
===================================================================================
Ljung-Box (L1) (Q):            0.04, 10.09   Jarque-Bera (JB):          11.24, 2.44
Prob(Q):                        0.83, 0.00   Prob(JB):                   0.00, 0.30
Heteroskedasticity (H):         0.45, 0.40   Skew:                      0.16, -0.38
Prob(H) (two-sided):            0.05, 0.03   Kurtosis:                   4.87, 3.44
                            Results for equation dln_inv
====================================================================================
                       coef    std err          z      P>|z|      [0.025      0.975]
------------------------------------------------------------------------------------
L1.dln_inv          -0.2408      0.093     -2.592      0.010      -0.423      -0.059
L1.dln_inc           0.2884      0.449      0.642      0.521      -0.592       1.169
L2.dln_inv          -0.1642      0.155     -1.059      0.290      -0.468       0.140
L2.dln_inc           0.0810      0.422      0.192      0.848      -0.746       0.908
beta.dln_consump     0.9523      0.639      1.490      0.136      -0.301       2.205
                            Results for equation dln_inc
====================================================================================
                       coef    std err          z      P>|z|      [0.025      0.975]
------------------------------------------------------------------------------------
L1.dln_inv           0.0631      0.036      1.761      0.078      -0.007       0.133
L1.dln_inc           0.0816      0.107      0.761      0.447      -0.129       0.292
L2.dln_inv           0.0106      0.033      0.321      0.748      -0.054       0.075
L2.dln_inc           0.0342      0.134      0.255      0.799      -0.229       0.297
beta.dln_consump     0.7734      0.112      6.886      0.000       0.553       0.994
                                  Error covariance matrix
============================================================================================
                               coef    std err          z      P>|z|      [0.025      0.975]
--------------------------------------------------------------------------------------------
sqrt.var.dln_inv             0.0434      0.004     12.294      0.000       0.036       0.050
sqrt.cov.dln_inv.dln_inc  5.494e-05      0.002      0.027      0.978      -0.004       0.004
sqrt.var.dln_inc             0.0109      0.001     11.215      0.000       0.009       0.013
============================================================================================

Warnings:
[1] Covariance matrix calculated using the outer product of gradients (complex-step).
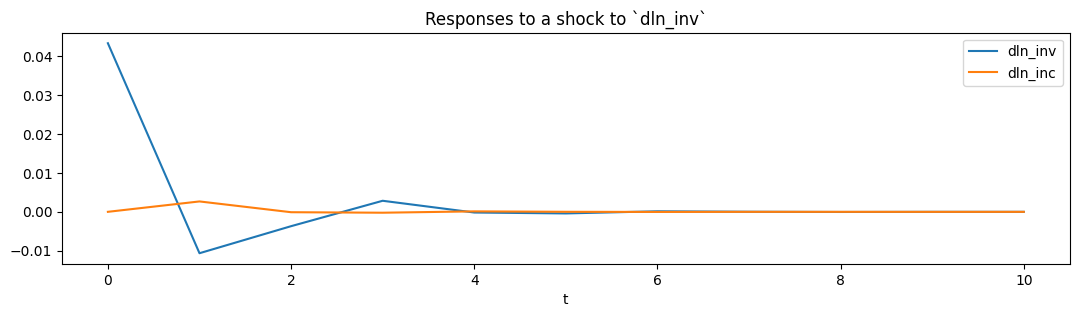
From the estimated VAR model, we can plot the impulse response functions of the endogenous variables.
[5]:
ax = res.impulse_responses(10, orthogonalized=True, impulse=[1, 0]).plot(
    figsize=(13, 3)
)
ax.set(xlabel="t", title="Responses to a shock to `dln_inv`");
Example 2: VMA#
A vector moving average model can also be formulated. Below we show a VMA(2) on the same data, but where the innovations to the process are uncorrelated. In this example we leave out the exogenous regressor but now include the constant term.
[6]:
mod = sm.tsa.VARMAX(
    endog[["dln_inv", "dln_inc"]], order=(0, 2), error_cov_type="diagonal"
)
res = mod.fit(maxiter=1000, disp=False)
print(res.summary())
                             Statespace Model Results
==================================================================================
Dep. Variable:     ['dln_inv', 'dln_inc']   No. Observations:                   75
Model:                             VMA(2)   Log Likelihood                 353.887
                              + intercept   AIC                           -683.774
Date:                    Tue, 27 Oct 2026   BIC                           -655.964
Time:                            22:10:38   HQIC                          -672.670
Sample:                        04-01-1960
                             - 10-01-1978
Covariance Type:                      opg
===================================================================================
Ljung-Box (L1) (Q):             0.00, 0.07   Jarque-Bera (JB):         12.73, 13.42
Prob(Q):                        0.95, 0.79   Prob(JB):                   0.00, 0.00
Heteroskedasticity (H):         0.44, 0.81   Skew:                      0.06, -0.48
Prob(H) (two-sided):            0.04, 0.60   Kurtosis:                   5.01, 4.83
                           Results for equation dln_inv
=================================================================================
                    coef    std err          z      P>|z|      [0.025      0.975]
---------------------------------------------------------------------------------
intercept         0.0182      0.005      3.794      0.000       0.009       0.028
L1.e(dln_inv)    -0.2583      0.106     -2.441      0.015      -0.466      -0.051
L1.e(dln_inc)     0.4999      0.631      0.792      0.428      -0.737       1.737
L2.e(dln_inv)     0.0313      0.149      0.210      0.834      -0.261       0.324
L2.e(dln_inc)     0.1927      0.476      0.405      0.686      -0.741       1.126
                           Results for equation dln_inc
=================================================================================
                    coef    std err          z      P>|z|      [0.025      0.975]
---------------------------------------------------------------------------------
intercept         0.0207      0.002     13.138      0.000       0.018       0.024
L1.e(dln_inv)     0.0476      0.042      1.145      0.252      -0.034       0.129
L1.e(dln_inc)    -0.0777      0.140     -0.557      0.578      -0.351       0.196
L2.e(dln_inv)     0.0184      0.042      0.433      0.665      -0.065       0.102
L2.e(dln_inc)     0.1229      0.153      0.804      0.421      -0.177       0.422
                             Error covariance matrix
==================================================================================
                     coef    std err          z      P>|z|      [0.025      0.975]
----------------------------------------------------------------------------------
sigma2.dln_inv     0.0020      0.000      7.354      0.000       0.001       0.003
sigma2.dln_inc     0.0001   2.33e-05      5.829      0.000       9e-05       0.000
==================================================================================

Warnings:
[1] Covariance matrix calculated using the outer product of gradients (complex-step).
Caution: VARMA(p,q) specifications#
Although the model allows estimating VARMA(p,q) specifications, these models are not identified without additional restrictions on the representation matrices, which are not built-in. For this reason, it is recommended that the user proceed with error (and indeed a warning is issued when these models are specified). Nonetheless, they may in some circumstances provide useful information.
[7]:
mod = sm.tsa.VARMAX(endog[["dln_inv", "dln_inc"]], order=(1, 1))
res = mod.fit(maxiter=1000, disp=False)
print(res.summary())
/tmp/ipykernel_4393/242493548.py:1: EstimationWarning: Estimation of VARMA(p,q) models is not generically robust, due especially to identification issues.
  mod = sm.tsa.VARMAX(endog[["dln_inv", "dln_inc"]], order=(1, 1))
                             Statespace Model Results
==================================================================================
Dep. Variable:     ['dln_inv', 'dln_inc']   No. Observations:                   75
Model:                         VARMA(1,1)   Log Likelihood                 354.294
                              + intercept   AIC                           -682.588
Date:                    Tue, 27 Oct 2026   BIC                           -652.461
Time:                            22:10:59   HQIC                          -670.559
Sample:                        04-01-1960
                             - 10-01-1978
Covariance Type:                      opg
===================================================================================
Ljung-Box (L1) (Q):             0.00, 0.07   Jarque-Bera (JB):         11.16, 14.06
Prob(Q):                        0.98, 0.79   Prob(JB):                   0.00, 0.00
Heteroskedasticity (H):         0.43, 0.91   Skew:                      0.02, -0.45
Prob(H) (two-sided):            0.04, 0.81   Kurtosis:                   4.89, 4.92
                           Results for equation dln_inv
=================================================================================
                    coef    std err          z      P>|z|      [0.025      0.975]
---------------------------------------------------------------------------------
intercept         0.0095      0.060      0.157      0.875      -0.109       0.128
L1.dln_inv       -0.0088      0.646     -0.014      0.989      -1.275       1.258
L1.dln_inc        0.4316      2.584      0.167      0.867      -4.633       5.497
L1.e(dln_inv)    -0.2439      0.656     -0.372      0.710      -1.529       1.041
L1.e(dln_inc)     0.1143      2.842      0.040      0.968      -5.456       5.685
                           Results for equation dln_inc
=================================================================================
                    coef    std err          z      P>|z|      [0.025      0.975]
---------------------------------------------------------------------------------
intercept         0.0163      0.025      0.653      0.514      -0.033       0.065
L1.dln_inv       -0.0299      0.258     -0.116      0.908      -0.536       0.476
L1.dln_inc        0.2424      1.017      0.238      0.812      -1.750       2.235
L1.e(dln_inv)     0.0865      0.265      0.327      0.744      -0.432       0.605
L1.e(dln_inc)    -0.2406      1.055     -0.228      0.820      -2.307       1.826
                                  Error covariance matrix
============================================================================================
                               coef    std err          z      P>|z|      [0.025      0.975]
--------------------------------------------------------------------------------------------
sqrt.var.dln_inv             0.0448      0.003     14.537      0.000       0.039       0.051
sqrt.cov.dln_inv.dln_inc     0.0017      0.003      0.660      0.510      -0.003       0.007
sqrt.var.dln_inc             0.0116      0.001     11.821      0.000       0.010       0.013
============================================================================================

Warnings:
[1] Covariance matrix calculated using the outer product of gradients (complex-step).